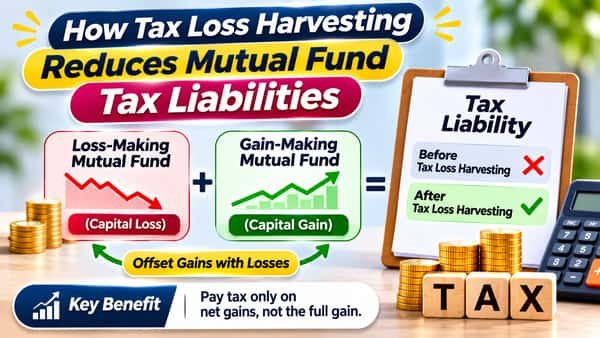
How tax loss harvesting reduces mutual fund tax liabilities comes down to one move: you sell a fund that’s below your purchase cost, book the loss and use it to cancel taxable gains elsewhere, so you pay less on the gains you’ve already made. In India, a short-term loss can wipe out both short-term and long-term gains, a long-term loss can only wipe out long-term gains, and unused losses carry forward for eight years if you file on time. This is general information, not tax advice.
Quick Facts
| Rule | What it means |
|---|---|
| Equity STCG (12 months or less) | Taxed at 20% under Section 111A |
| Equity LTCG (over 12 months) | 12.5% on gains above ₹1.25 lakh a year, under Section 112A |
| Short-term capital loss | Can offset short-term and long-term gains |
| Long-term capital loss | Can offset only long-term gains |
| Carry-forward | Up to 8 assessment years, if the return is filed by the due date |
| Wash-sale rule | None in India, according to several guides |
How It Works
The idea is to realise a loss on purpose.
- Tax-loss harvesting involves selling securities at a loss to generate capital losses that offset taxable capital gains, and it’s a legal strategy under the Income Tax Act, according to Share.Market
- Once you sell, the loss is booked and can be set off against gains in the same year
- You can then buy the same fund again, or a similar one, to stay invested, since India has no wash-sale rule, according to several guides
The Set-Off Rules
Which loss offsets which gain decides the saving.
- A short-term capital loss can be set off against both STCG and LTCG
- A long-term capital loss can be set off only against LTCG, so it can’t reduce short-term gains
- Losses can’t be set off against salary or business income, according to Finplann
- Current-year losses are set off first, then brought-forward losses, according to StartupSuccessStories
A Worked Example: Loss Against Long-Term Gains
Numbers from Value Research show the effect.
- Say your equity LTCG for the year is ₹3 lakh, and you have a short-term loss of ₹1 lakh
- Without harvesting, taxable LTCG is ₹3 lakh minus ₹1.25 lakh, or ₹1.75 lakh, and tax at 12.5% is ₹21,875
- With harvesting, net LTCG is ₹2 lakh, taxable LTCG is ₹75,000 and tax is ₹9,375
- The saving is ₹12,500, before exit loads and other frictions
- It’s 12.5% of the loss, not 20%, because the loss reduced LTCG, not STCG
A Second Example: Loss Against Short-Term Gains
Offsetting the higher-taxed gain saves more.
- Suppose you have STCG of ₹2 lakh and a short-term loss of ₹1 lakh
- Offsetting it against STCG cuts tax by 20% of ₹1 lakh, or ₹20,000, before cess, by my arithmetic
- That’s why one guide advises offsetting STCG first, since it carries the highest rate of 20%
- A long-term loss can’t do this, so it’s less valuable
When It Doesn’t Help
The exemption can waste a loss.
- If your LTCG is below ₹1.25 lakh, it’s already tax-free, so a loss set against it saves nothing now
- For example, with LTCG of ₹1 lakh, tax is zero with or without the loss
- In that case, the loss is better carried forward, where it can offset gains in a later year, if you file on time
- Harvesting also doesn’t help if you have no gains this year and none expected
The Other Side: Harvesting Gains
You can use the exemption each year.
- The first ₹1.25 lakh of aggregate LTCG a year is tax-free, so some investors sell and rebuy to book that much gain and reset their cost base, according to WealthOrbit
- The most tax you can avoid this way is ₹15,625 a year at 12.5%, before cess, my arithmetic
- The exemption applies to total LTCG from all equity shares and equity-oriented funds, not per fund, according to Maxiom Wealth
- Selling a unit that’s near the 12-month mark and rebuying converts the next gain from potential long-term to short-term, which costs more, according to Dealplexus
Carry-Forward and Filing
Losses only help if you report them.
- Unabsorbed capital losses carry forward for up to 8 assessment years under Section 74
- You must file your return by the due date under Section 139(1), usually 31 July, and a belated return forfeits the carry-forward, according to StartupSuccessStories and Stockcalc
- Use ITR-2 or ITR-3 and report the losses, according to Stockcalc
- Keep records of every sale and purchase, including contract notes and capital gains statements
Debt and Hybrid Funds
The rules differ by fund type.
- Equity-oriented funds, with at least 65% in equity, follow the rates above
- Debt-oriented funds are taxed at slab rates regardless of holding period, according to Finplann, though that guide uses the old 35%-equity definition, and the definition of specified funds changed from FY 2025-26
- As I understand it, gains and losses on such funds are treated as short-term, so a loss behaves as a short-term loss, but check with a chartered accountant
- Hybrid funds with 35% to 65% equity are taxed at 12.5% after 24 months, and at slab rates before that
The Costs
Harvesting isn’t free.
- Exit loads can eat into the saving, according to Value Research
- Time out of the market means you could miss gains before you rebuy
- SIP units are sold first-in, first-out, so a recent instalment may be the one you sell, and the loss depends on its purchase price
- A sale that triggers tax elsewhere defeats the purpose
Do the Rules Still Work in 2026?
The framework is stable.
- One source says the core capital gains framework set in July 2024 remains fully in place after the Finance Act 2025 and Budget 2026
- The Income-tax Act, 2025 now applies, so section numbers such as 111A and 112A may be renumbered, but rates and set-off rules are described as unchanged in the guides I found
- Confirm current rules with a chartered accountant before acting
FAQs
What is tax loss harvesting in mutual funds?
Selling a fund at a loss to book a capital loss and use it to offset taxable gains, then reinvesting if you want to stay invested.
Can a long-term loss offset short-term gains?
No. A long-term capital loss can be set off only against long-term gains, while a short-term loss can offset both.
How long can I carry forward capital losses?
Up to 8 assessment years, provided you file your return by the due date under Section 139(1).
Is there a wash-sale rule in India?
Several guides say no, so you can repurchase immediately, though you should check with a chartered accountant.
How much can I save?
For example, ₹12,500 on a ₹1 lakh short-term loss set against LTCG above the exemption, or ₹20,000 if set against short-term gains.