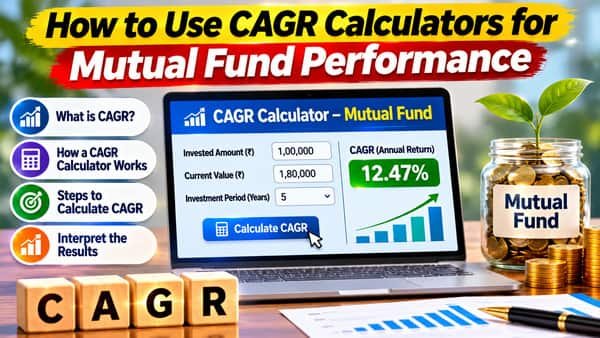
How to use CAGR calculators for mutual fund performance starts with picking the right job for them: they turn one starting value and one ending value into a smooth yearly rate, so they suit lump sums held for more than a year and mislead on SIPs. Used well, they let you compare funds fairly. Used carelessly, they hide the bumps that made the number. This is general information, not investment advice, and the examples marked as hypothetical are mine.
Which Measure for Which Situation
| Your situation | Measure to use | Why |
|---|---|---|
| Lump sum held over a year | CAGR | One start value, one end value |
| SIP or any series of investments | XIRR | Handles cash flows on different dates |
| Anything under a year | Absolute return | Annualising a short period distorts it |
| Comparing funds | CAGR over identical dates, plus rolling returns | A single window can mislead |
| Planning a goal | CAGR rearranged for required return | Works backwards from a target |
The Formula and the Three Inputs
CAGR is simple enough to do by hand.
- CAGR = (Ending Value ÷ Beginning Value)^(1 ÷ Years) − 1, as ClearTax and Bajaj AMC give it
- You need the beginning value, the ending value and the number of years
- In Excel it’s =(A2/A1)^(1/A3)-1, according to one guide
- The ending value comes from the fund’s NAV, so it’s already net of the expense ratio, according to Toolsuite
Two Worked Examples
Plain numbers show how it behaves.
- Bajaj AMC’s example: ₹1,00,000 growing to ₹1,50,000 over three years gives a CAGR of about 14.5%, my arithmetic
- A different example: ₹1,00,000 growing to ₹1,80,000 over five years gives about 12.5%
- In both cases, the calculator reports the steady rate that would have produced the same result, not what happened in any given year
- Absolute return for the first example would simply be 50%, which says nothing about the time taken
Step by Step
A short routine avoids most errors.
- Pick the dates and note the NAV or investment value on each, using the Growth plan
- Count the years precisely, treating 12 months as one year and dividing days by 365 for partial years
- Enter beginning value, ending value and years
- Record the CAGR and the dates alongside it
- Repeat for the fund’s benchmark and one or two peers over identical dates
Why SIPs Break It
The tool assumes one deposit.
- CAGR is designed for one beginning value and one ending value, so it can’t handle several instalments on different dates, according to Bajaj AMC
- XIRR calculates the return for multiple cash flows at different intervals and is generally the more suitable measure for SIPs, according to Axis Mutual Fund and others
- Zerodha Varsity sums it up: lump sum over a year, CAGR; SIP over a year, XIRR; anything shorter, absolute return
- For a single lump sum, XIRR and CAGR give essentially the same answer, since XIRR is a modified form of CAGR
The Date Trap
The result depends heavily on where you start and stop.
- Take a hypothetical fund whose NAV was ₹20 five years ago
- If the NAV is ₹32 today, the CAGR is about 9.9%
- If you happen to measure at a market peak when the NAV is ₹40, the CAGR jumps to about 14.9%, my arithmetic
- Same fund, same manager, five points apart, which is why a single CAGR deserves suspicion
- Rolling returns, which look at many overlapping windows, give a fairer picture, and several guides recommend using CAGR alongside them
What CAGR Hides
A smooth rate flatters a bumpy ride.
- It considers only the beginning and ending values, so two investments can share a CAGR even if their year-to-year performance differs wildly, according to Bajaj AMC
- It doesn’t show volatility or the drawdowns an investor had to sit through, according to 5paisa
- It assumes steady growth, which no equity fund delivers
- Look at yearly returns and the worst fall as well, since a 14% CAGR that included a 30% crash feels very different from a gentle climb
Making Comparisons Fair
Several traps catch beginners.
- Same dates: compare funds over identical periods, not each fund’s own history
- Same plan type: compare Direct with Direct and Regular with Regular, since the expense ratio differs
- Growth versus IDCW: if a fund pays IDCW, the payouts reduce the NAV, so NAV-based CAGR understates what an investor earned. Use the Growth plan or a total-return figure
- Same category: a small-cap fund and a large-cap fund shouldn’t be judged by one number
- Same benchmark: check the fund against its stated benchmark and category average
CAGR Versus Absolute Return
They answer different questions.
- Absolute return is the total percentage change, regardless of time, and is commonly used for periods of a year or less, according to Bajaj AMC
- Cleartax says to use CAGR for investments longer than one year
- Comparing the two without noting the period is a common mistake, according to 5paisa, as is assuming CAGR is the return earned every year
- A 40% absolute return over two years and over ten years are very different results
Working Backwards for Goals
The formula runs in reverse.
- Required CAGR = (Target ÷ Current)^(1 ÷ Years) − 1
- To grow ₹10 lakh to ₹25 lakh in ten years you’d need about 9.6% a year, my arithmetic
- That gives you a reality check against a fund’s own CAGR record before you commit
- It’s a planning aid, since the number says nothing about what the fund will deliver
Tax and Costs
The calculator ignores two things.
- CAGR from NAV is net of fund expenses but before tax, according to Toolsuite’s note on NAV
- Equity LTCG above ₹1.25 lakh a year is taxed at 12.5% and STCG at 20%, per the rules covered earlier in this series, so your post-tax return will be lower once gains exceed the exemption
- In the first example, a gain of ₹50,000 falls within the exemption, so the post-tax figure would be the same, but larger gains wouldn’t be
Reading a Fund’s Published Returns
A few checks help.
- Factsheets and platforms usually quote 1-year, 3-year, 5-year and since-inception figures, and you should check which are annualised
- Returns under a year are typically shown as absolute, as Varsity notes, while longer periods are annualised
- I couldn’t confirm the exact regulatory convention from these sources, so read the notes on the factsheet
- “Since inception” figures can flatter an old fund that started in a very different market
Where the Sources Disagree
There are small conflicts.
- One guide says AMFI-regulated platforms recommend XIRR for SIPs, which I couldn’t verify, though the XIRR advice itself is consistent across sources
- ClearTax says to use CAGR for periods over one year, while Bajaj AMC says CAGR is typically used for longer periods, with shorter durations distorting results
- Rounding differs, so a result like 8.44% versus 8.45% isn’t an error
FAQs
Q1. What is CAGR in mutual funds?
A. CAGR, or Compound Annual Growth Rate, represents the steady annual rate at which an investment would have grown from its starting value to its ending value over a specified period. It is calculated using the formula (Ending Value ÷ Starting Value)^(1 ÷ Number of Years) − 1.
Q2. Can I use a CAGR calculator for SIPs?
A. Not reliably. CAGR is designed primarily for a single lump-sum investment with one starting and one ending value. For SIPs involving multiple investments made on different dates, XIRR (Extended Internal Rate of Return) is generally a more appropriate measure.
Q3. Is a higher CAGR always a better mutual fund?
A. No. A higher CAGR alone does not necessarily mean a fund is better. CAGR depends heavily on the selected start and end dates and does not show volatility during the period. Funds should be compared over identical periods while also considering rolling returns, consistency, risk, and investment objectives.
Q4. Does CAGR include mutual fund expenses and tax?
A. When CAGR is calculated using a mutual fund’s NAV, fund expenses reflected in the NAV are already accounted for. However, CAGR generally does not represent an investor’s post-tax return. The actual amount an investor receives can differ after applicable capital gains taxes and other investor-specific costs.